Mastercard’s 2024 announcement set out a vision for simpler, more secure digital checkout. It is an industry roadmap, not a guarantee that fraud will be virtually eliminated.
Mastercard aims to eliminate manual card entry and one-time or static passwords for online transactions across its network by 2030, using tokenization and payment passkeys. Biometric or device authentication can support this vision. Numberless physical cards are a related innovation, not a universal legal requirement to replace every card.
This bold vision addresses a pressing global issue: the rise in online Fraud.
Ecommerce fraud creates significant losses for merchants.
This article explores Mastercard’s innovations, the challenges they present, and their broader implications for the payment ecosystem.
Current State of Payment Security
The rapid growth of digital payments has revolutionized global commerce, yet it has also intensified the risk of cybercrime.
Juniper Research forecast more than $362 billion in cumulative online-payment fraud losses between 2023 and 2028. This is a multi-year projection, not annual observed losses or a current 2026 total.
Mastercard’s 2024 announcement described online fraud as seven times higher than in-person fraud within its stated comparison. This is a network-reported historical comparison, not a universal ratio for every payment mix.
Tokenization has emerged as a vital defense mechanism in this payment sector.
Tokenization replaces a primary account number with a payment token whose use can be restricted to a device, merchant or payment context. It reduces exposure of reusable card details, but tokens and payment systems still require security controls.
Tokenization adoption and fraud comparisons depend on the network’s scope and timeframe.
Transaction volume and tokenization share are different measures.
Current security measures, however, fall short of addressing all risks.
Credential theft remains a risk, but manual card entry, one-time codes, passwords and payment passkeys are distinct mechanisms.
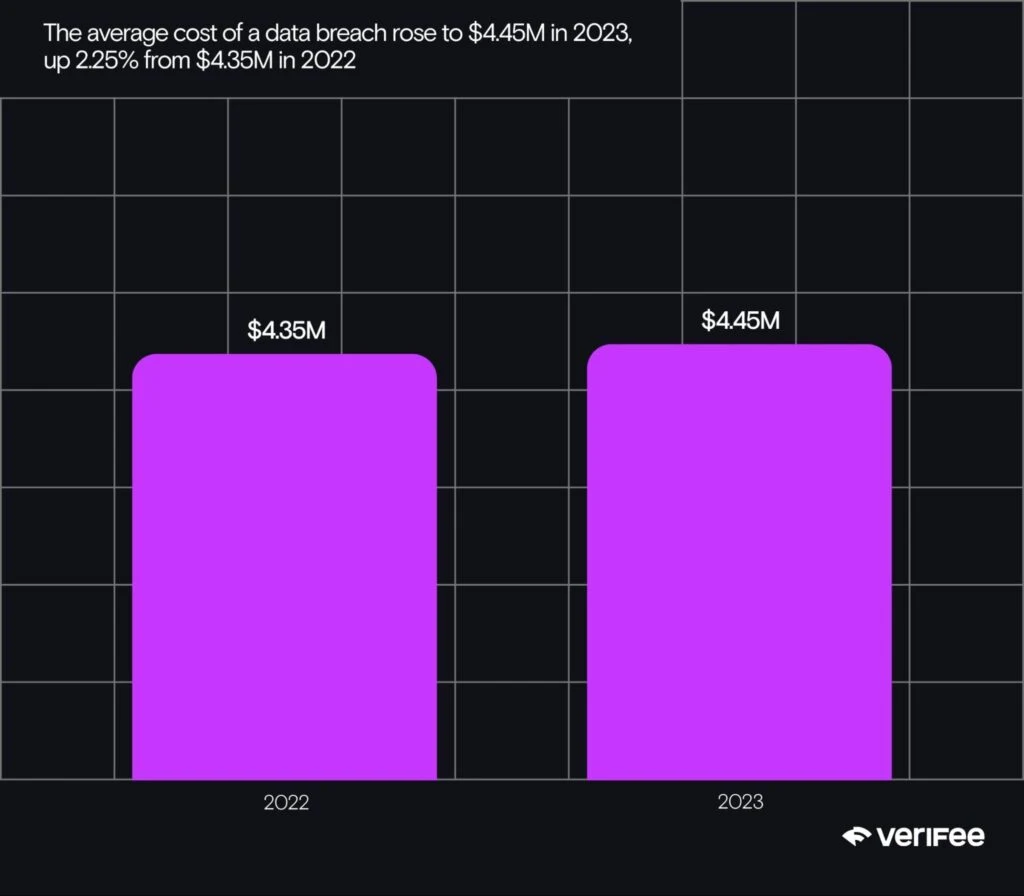
IBM’s 2023 Cost of a Data Breach report found an average cost of $4.45 million across studied organizations, up from $4.35 million in 2022, or about 2.3%. This sample average is not a prediction of losses for a small merchant and is not an ecommerce chargeback total.
For businesses, these costs often include not just Fraud losses but also reputational damage and Compliance penalties.
Consumers are also feeling the impact.
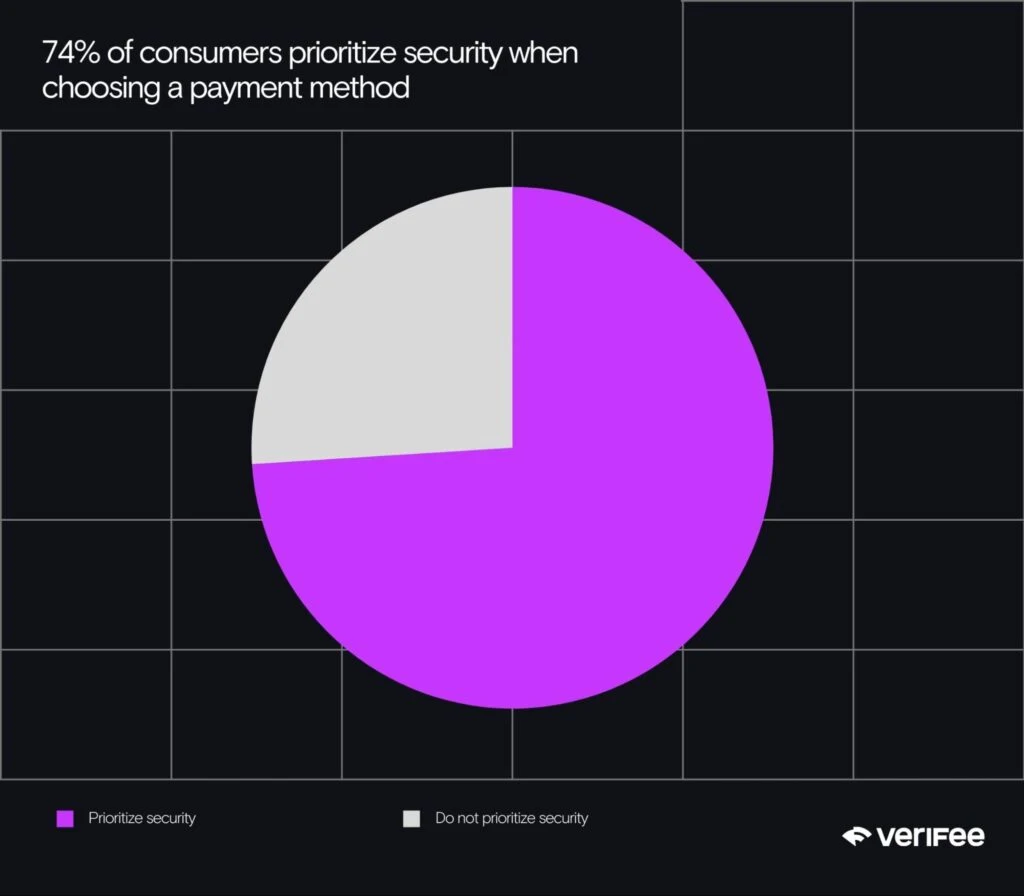
This Consumer demand aligns with the need for innovations that Balance security with ease of use.
Economic considerations compound these challenges.
Chargeback fees, disputed payment value and total economic loss are different measures and must not be added indiscriminately.
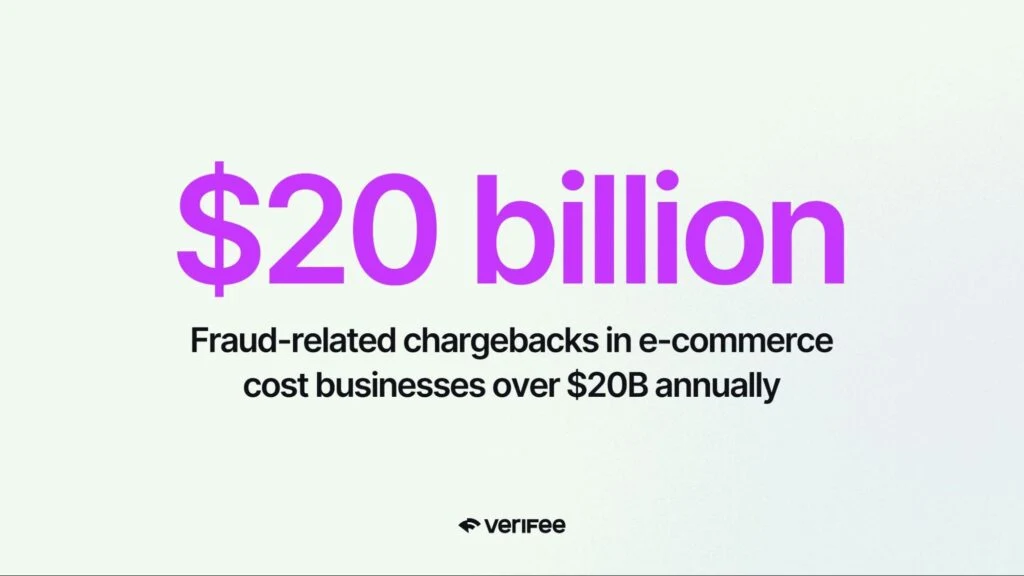
As a result, companies are under growing pressure to adopt robust security measures that mitigate Fraud without inflating operational costs.
Innovations by Mastercard
Mastercard is at the forefront of advancing payment security, employing cutting-edge technologies like Tokenization, numberless cards, and biometric authentication to combat escalating online Fraud.
These innovations aim to enhance security while streamlining the payment experience for consumers and businesses alike.
Tokenization and Payment Passkeys
Tokenization is central to Mastercard’s strategy, replacing sensitive card details with unique identifiers that are useless to cybercriminals.
The company has introduced payment passkeys, enabling users to authenticate transactions with biometrics or device credentials rather than Manual Entry.
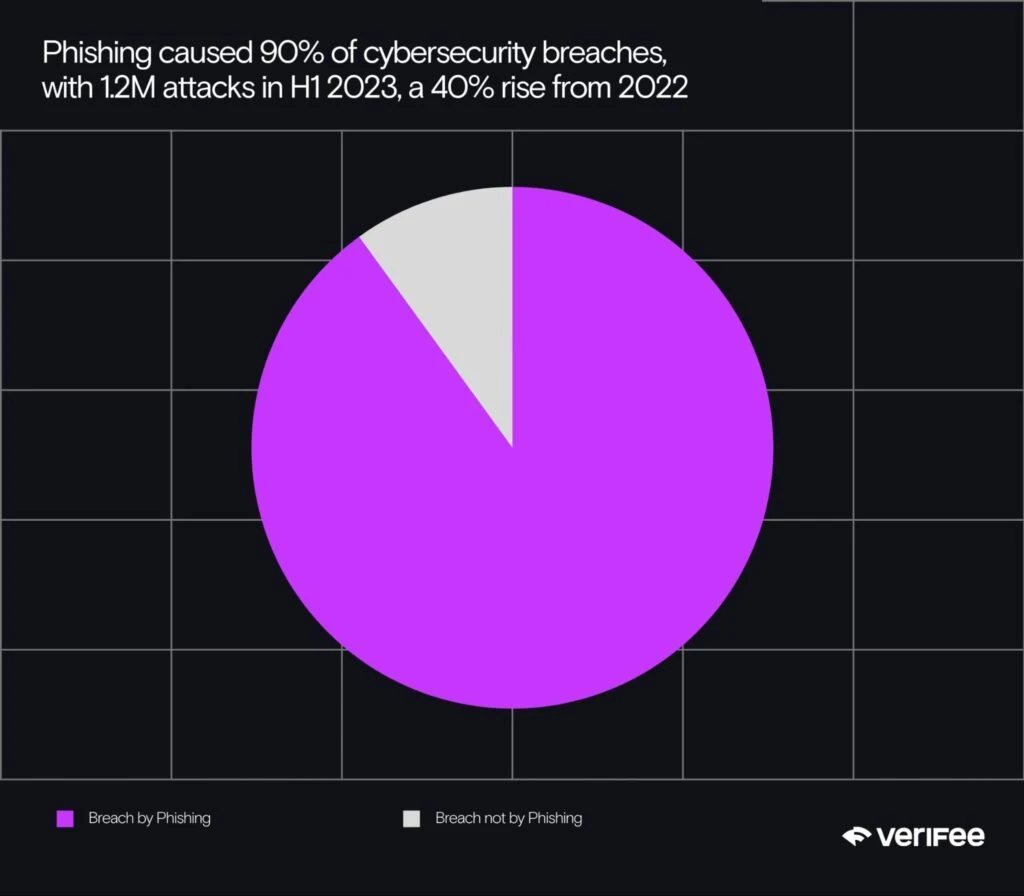
Passkeys can reduce reliance on shared secrets and provide phishing-resistant authentication when properly implemented.
Numberless Cards
The transition to numberless physical Cards is another cornerstone of Mastercard’s innovation.
Numberless cards omit printed account details, reducing casual exposure of those details. They still have underlying account credentials and a lost card may still be misused. Issuer controls, authentication and prompt loss reporting remain important.
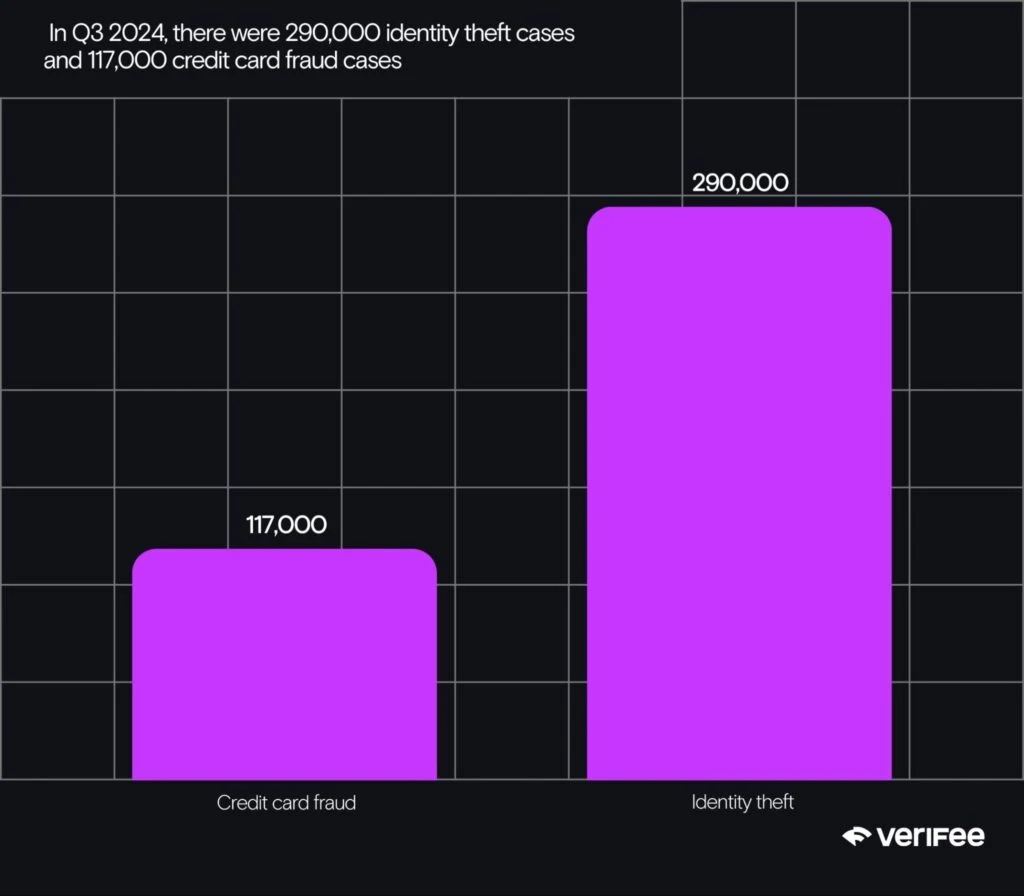
Credit-card fraud can overlap with identity theft. Reported complaints are not a count of all incidents.
biometric authentication
Mastercard’s embrace of biometric technology represents a breakthrough in digital payment security.
Technologies such as fingerprint scanning, facial recognition, and iris scans are becoming mainstream.
Biometric-payment market estimates have a defined product scope that differs from card-network transaction value.
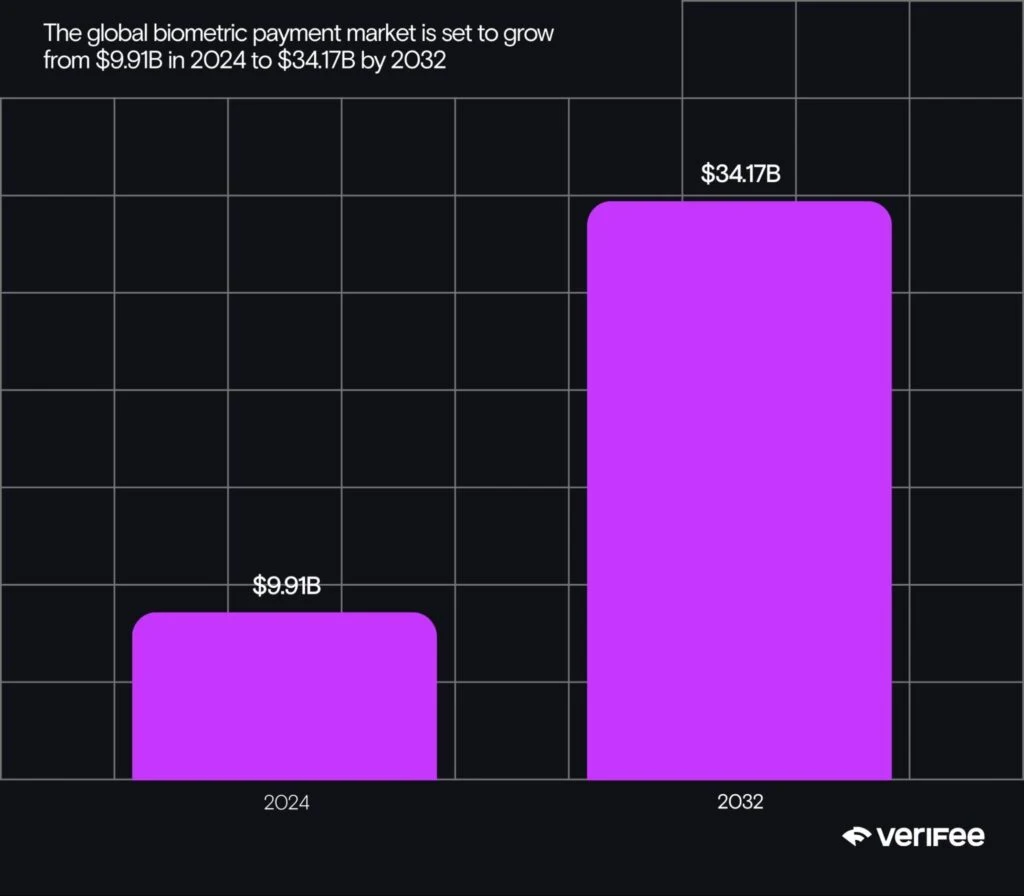
Biometric authentication can reduce reliance on memorized passwords. For device-bound passkeys, a fingerprint or facial check generally unlocks a device credential locally rather than sharing a biometric template with the merchant. Biometric payment schemes vary and require privacy, recovery and fallback controls.
Challenges and Considerations
While Mastercard’s innovations in payment security represent a significant leap forward, they also introduce challenges for businesses and consumers that warrant careful evaluation.
The adoption of Tokenization, biometric authentication, and numberless cards creates technical, operational, and financial considerations that must be addressed to ensure equitable benefits across the payment ecosystem.
Increased Costs for Merchants
The implementation of advanced payment technologies often comes with additional expenses for businesses.
Integrating Tokenization and biometric authentication systems could increase merchant processing fees.
Payment processors may impose these fees to cover the costs of technology upgrades, Compliance, and ongoing maintenance.
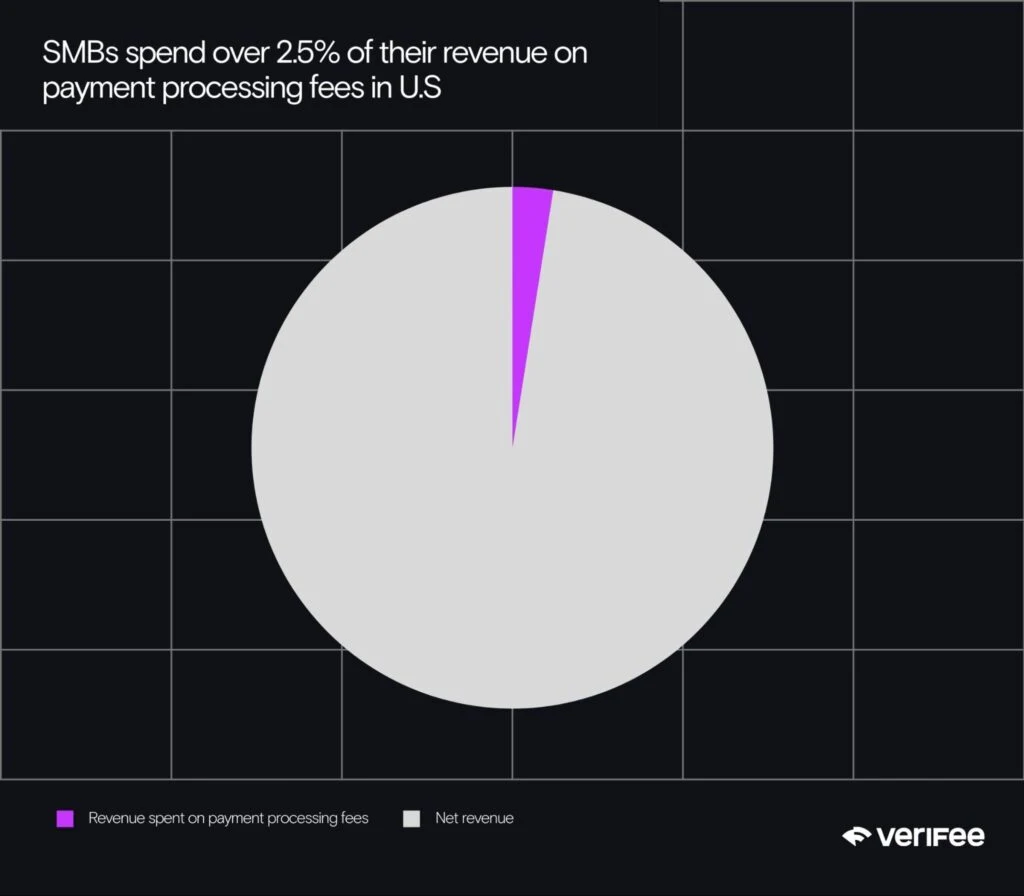
Historically, such expenses are passed on to merchants, creating concerns about the financial burden for small and medium-sized businesses (SMBs).
The original 2.5% of revenue processing-cost claim links to a processor’s blog, not a verified NFIB study. Do not treat it as a national small-business average. Measure your actual fee-to-card-volume ratio and distinguish card volume from total revenue.
Data Migration and System Compatibility
The shift to Tokenization and numberless cards presents logistical challenges for merchants.
Migrating customer data securely can be a complex and resource-intensive process, with businesses citing compatibility issues with legacy systems.
Additionally, these technologies could inadvertently lock businesses into specific payment processors, limiting their flexibility to negotiate better terms or switch providers. This “vendor lock-in” risk raises long-term strategic concerns for merchants.
Consumer Adoption and Accessibility
While biometric technologies offer enhanced security, they also raise accessibility concerns.
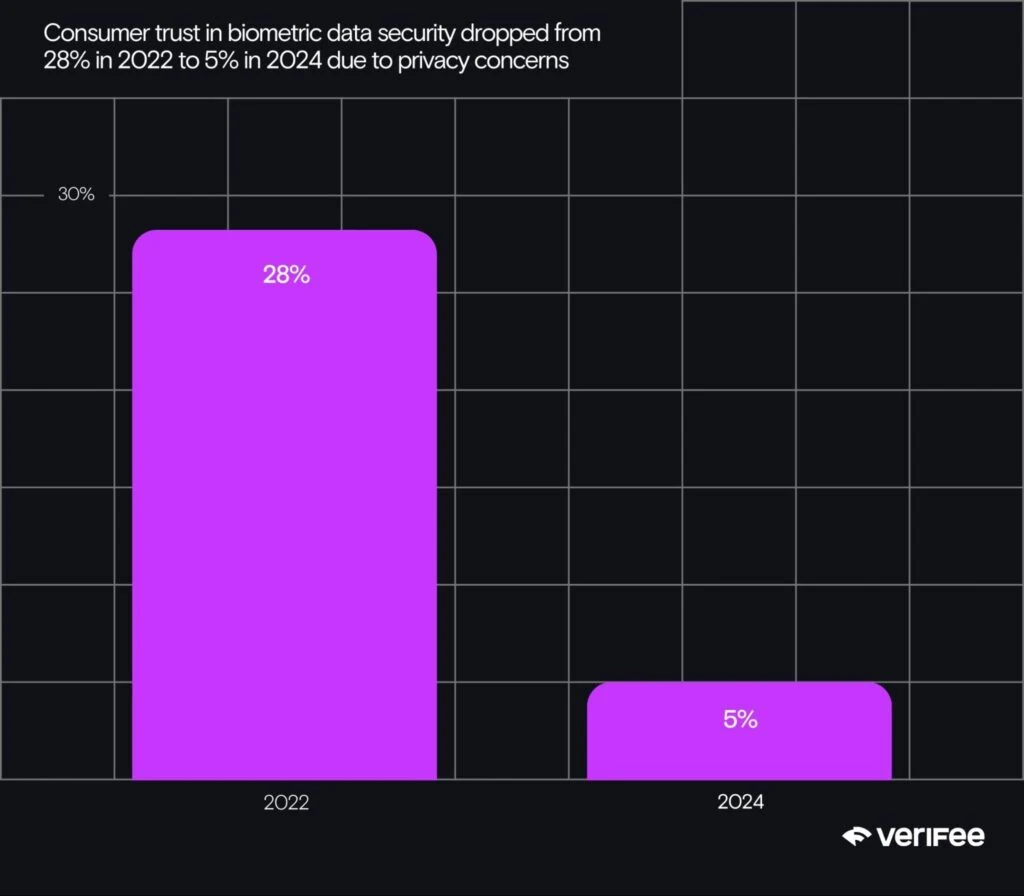
Moreover, some populations, including the elderly and individuals with disabilities, may face barriers to using these systems effectively.
Bridging these gaps will require industry-wide collaboration and user-centered design approaches.
Regulatory and Compliance Hurdles
Adopting these innovations means navigating an increasingly complex regulatory landscape.
PCI DSS obligations depend on how account data is stored, processed and transmitted and on the merchant’s validation requirements. The cited $50,000–$200,000 range is a vendor estimate, not an official mandatory annual fee. Many merchants use an eligible self-assessment route rather than a Report on Compliance. Confirm requirements with your acquirer and qualified assessor.
Broader Impact on Businesses and Consumers
Mastercard’s innovations, including Tokenization, biometric authentication, and numberless cards, extend beyond Fraud prevention to significantly influence the payment ecosystem for both businesses and consumers.
These advancements promise enhanced security, operational efficiency, and improved trust, but they also require strategic adaptation to maximize their benefits.
Enhanced Security and Reduced Fraud Costs
Tokenization and biometric authentication directly address vulnerabilities in digital transactions, especially in Card Not Present (CNP) scenarios.
Card-not-present fraud, all ecommerce fraud and worldwide digital fraud are different measures.
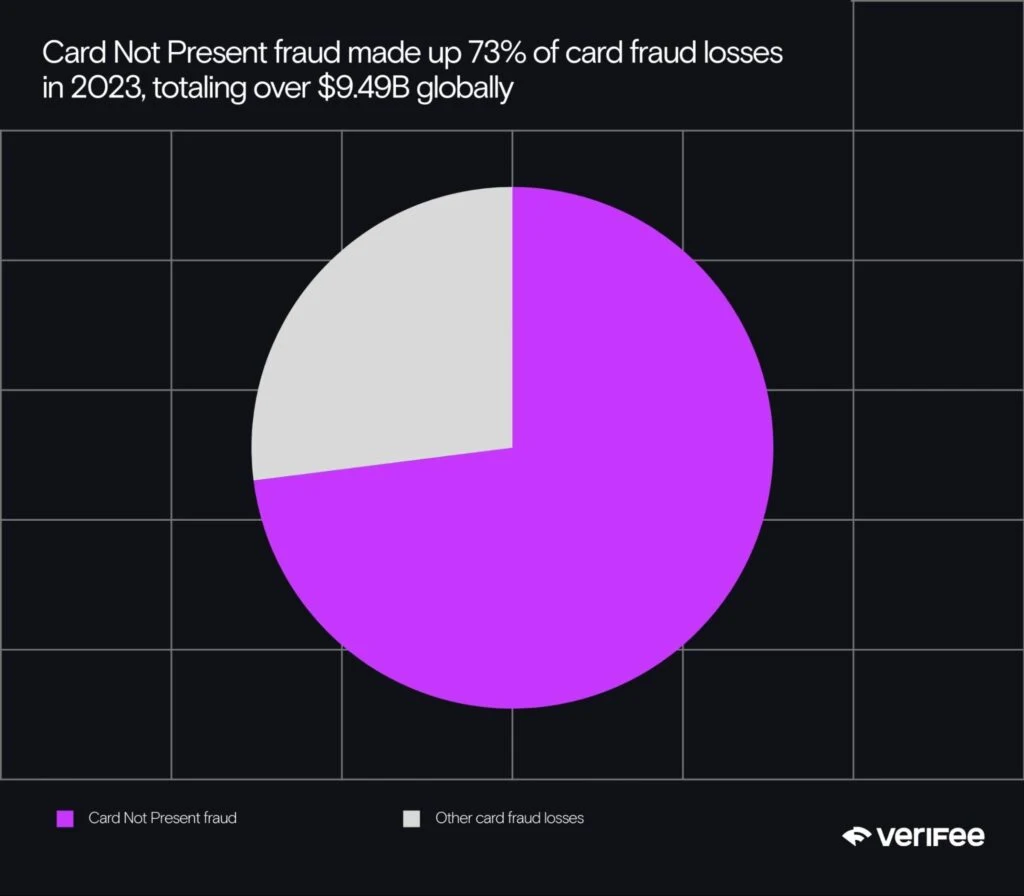
By replacing sensitive card information with tokenized data and utilizing biometric verifications, this solution can reduce Fraud incidents.
These controls may lower fraud and disputes, but chargeback outcomes and liability depend on the payment flow, authentication, network rules and merchant agreement. Better security is not a guarantee of fewer fees or savings.
Building Consumer Trust and Loyalty
Consumer trust is a cornerstone of successful digital commerce, and Mastercard’s innovations provide businesses with tools to strengthen that trust.
Mastercard’s Tokenization and biometric solutions empower businesses to visibly demonstrate their commitment to safeguarding sensitive customer data.
This proactive approach not only mitigates security risks but also builds long-term loyalty.
Furthermore, enhanced payment security aligns with growing Consumer demand for seamless transactions.
Operational Efficiency and Global Compliance
By integrating Mastercard’s technologies, businesses can improve operational efficiency.
Passwordless flows may reduce some reset requests. The original $1 million annual support-cost assertion comes from historical secondary reporting of a Forrester estimate, not a current measured cost for every U.S. company. Calculate the effect using your own support volumes and recovery processes.
Tokenization may reduce exposure or scope in appropriate implementations, but it does not automatically remove PCI DSS or privacy obligations. Confirm scope and controls for your integration rather than assuming that a new technology makes the regulatory landscape simple.
Addressing Small Business Challenges
For small businesses, adopting these technologies may feel daunting due to costs and resource limitations.
However, Mastercard’s partnerships with payment processors and FinTech firms aim to offer scalable solutions tailored to smaller enterprises.
By reducing Fraud-related losses and enabling access to secure payment ecosystems, these advancements can help level the playing field for SMBs in an increasingly digital Marketplace.
Looking Ahead to 2030
Mastercard’s bold vision of eliminating manual card entry and passwords by 2030 represents a pivotal moment in the fight against online Fraud.
Mastercard’s 2030 target is a roadmap, not a guarantee that every merchant or payment method will stop using existing credentials by that date.
The question now is: Will your business be ready to lead this change?
At VeriFee, we’re committed to empowering businesses with the tools and insights needed to navigate these changes.
Businesses can reduce Fraud, enhance customer trust, and streamline operations by adopting these innovative technologies and maintaining Compliance with global standards.
The road to 2030 is a call to action. These advancements offer more than just security, they represent a shift toward greater efficiency and customer loyalty.
Join VeriFee in planning for this future. Together, we can work toward a safer, more accessible payments ecosystem.