Buy Now, Pay Later (BNPL) offers customers the flexibility to spread payments over time, promising affordability without immediate financial strain.
For merchants, the promise is equally enticing, reduced Cart Abandonment, access to younger demographics, and a significant boost in sales. In fact, adoption rates among Gen Z, a key demographic driving BNPL growth, are projected to rise from 36.8% in 2021 to a forecast 47.4% for 2025.
But beneath this surge in popularity, the hidden costs, regulatory challenges, and operational trade-offs of BNPL often remain in the background until they hit the bottom line.
Is BNPL a catalyst for sustainable growth, a financial pitfall, or a nuanced combination of both?
Let’s get this right.
What Makes BNPL So Popular?
The rise of Buy Now, Pay Later (BNPL) is driven by Clear advantages that align with modern Consumer behavior and Merchant needs. Its appeal is in bridging financial flexibility for shoppers with sales opportunities for businesses.
BNPL has become a cornerstone of contemporary commerce because of these potential benefits:
Higher Sales and Conversion Rates
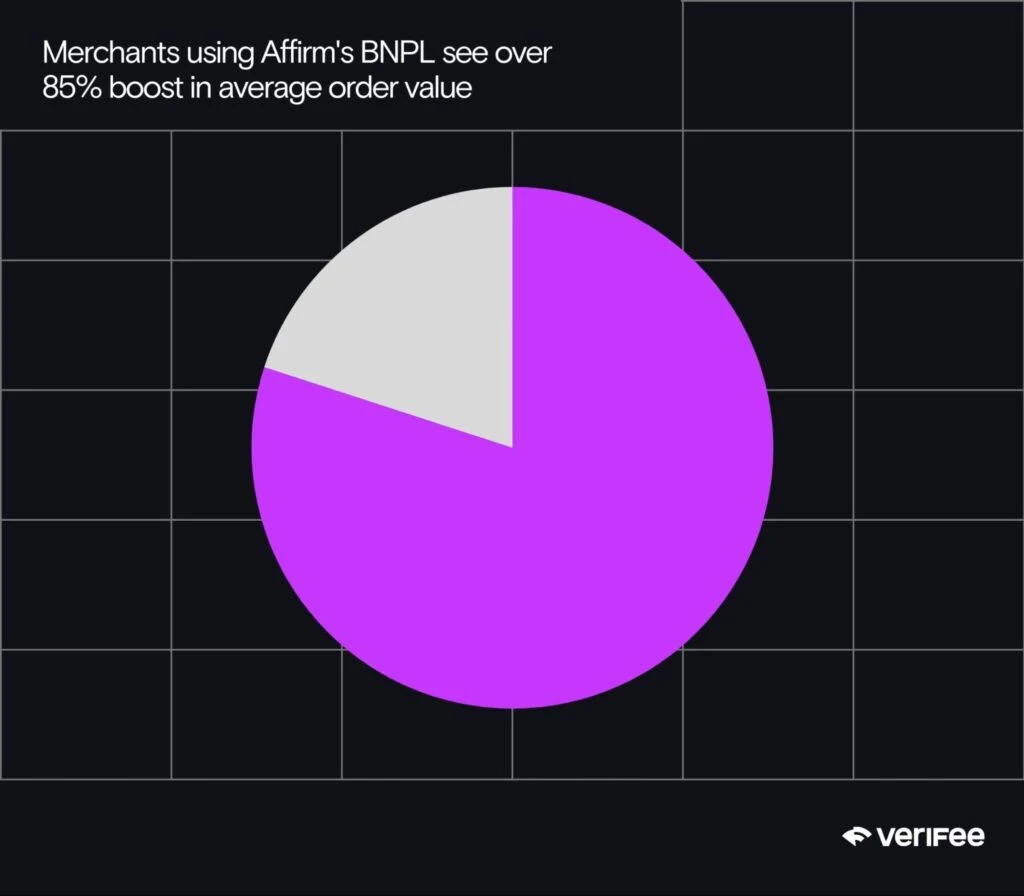
BNPL can make purchases feel more attainable. Affirm describes businesses reporting higher order values compared with other payment methods.
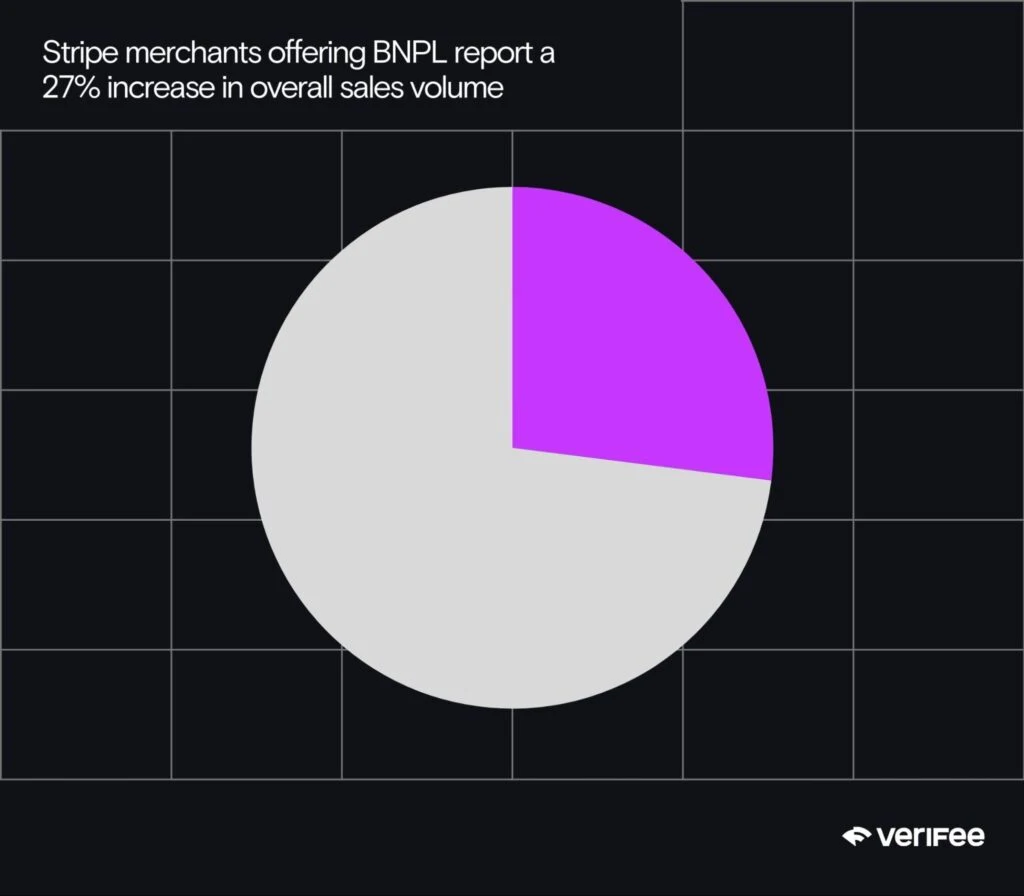
Stripe reported a 27% sales-volume increase in its tested BNPL checkout setting. Read Stripe’s experiment and methodology. Treat that as study-specific evidence, not a forecast for your business.
Tapping into New Customer Segments
For younger shoppers, such as Millennials and Gen Z, BNPL offers an attractive alternative to traditional credit Cards. A significant percentage of these demographics avoid credit Cards due to concerns about high interest rates and fees.
Merchants can appeal to these tech-savvy, financially conscious groups and gain access to a broader audience of digital-first consumers by embracing BNPL.
Instant Payments for Businesses
Despite allowing customers to pay over time, BNPL providers generally settle eligible purchases with merchants, net of fees, without waiting for the shopper to finish every installment. Settlement timing, holds, reserves, refunds and merchant recourse depend on the agreement. Shifting consumer repayment collection to the lender does not remove every merchant risk.
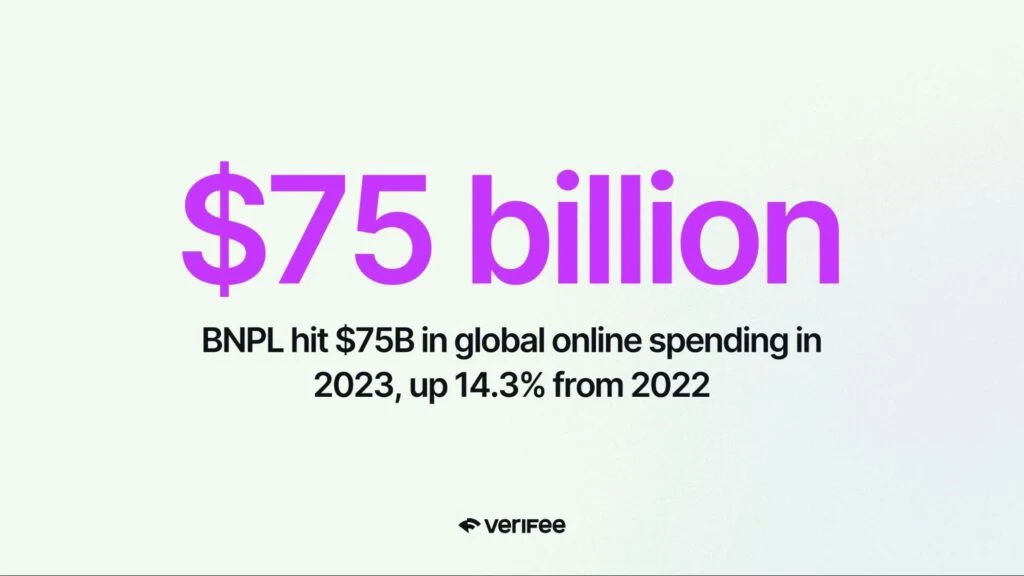
Growing Consumer Adoption
Behavioral Impact
BNPL reduces the psychological friction that often deters shoppers from completing a Sale by breaking down large purchases into smaller, manageable payments. This tactic leverages behavioral psychology to drive impulse purchases, making consumers feel more comfortable with larger spending decisions.
While these benefits paint an attractive picture, they are only one side of the coin.
The Hidden Cost Of Buy Now Pay Later (BNPL)
BNPL’s appeal is undeniable, but its benefits come with significant trade-offs that merchants cannot afford to overlook.
While offering customers the convenience of deferred payments can boost sales, the hidden costs often erode the perceived gains.
High Transaction Fees
BNPL providers charge fees between 1.5% and 7% per transaction, as a historical published range. Actual pricing depends on the lender, product, merchant and agreement and may include a fixed fee. Compare the complete quote with your actual alternative payment cost, not a universal card-rate assumption. For merchants operating on tight margins, these fees can cut deeply into profitability.
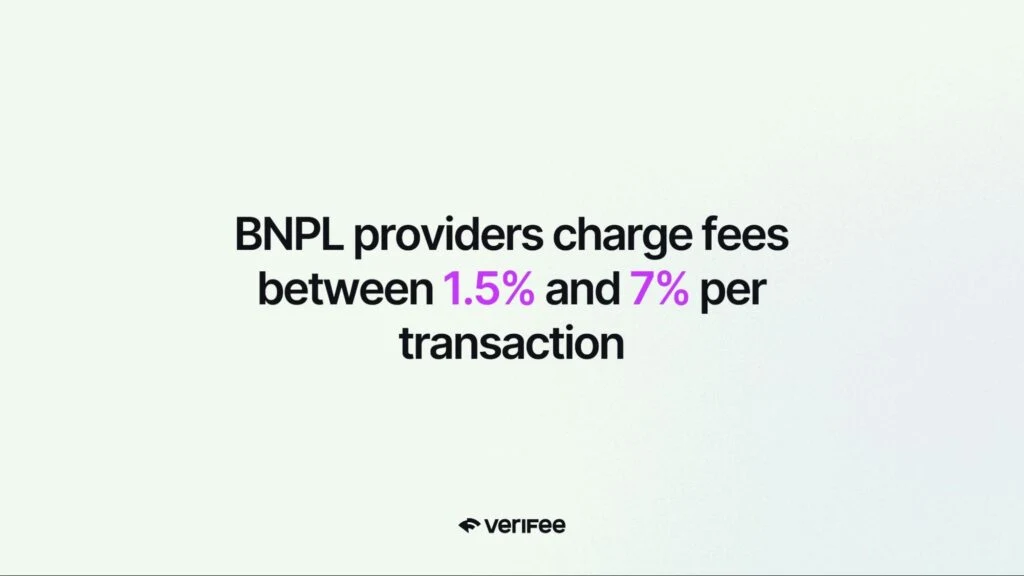
For instance, on $10,000 in BNPL sales, fees at a 5% rate would cost $500 which is an expense compared to traditional payment options.
Increased Returns and Disputes
Flexible payment options may influence purchase behavior, but the cited study does not establish that BNPL causes more returns than other methods. The CFPB’s five-lender market report found that 13% of the dollar value of 2021 purchases was returned or disputed. It is not a transaction-count return rate or a universal forecast. Returns can reduce retained revenue and create restocking, shipping and support costs.
Customer Experience Risks
When a BNPL provider mishandles a Dispute or fails to deliver a seamless experience, it is often the Merchant’s reputation that suffers.
Customers typically associate their frustrations with the business they purchased from, not the payment platform, creating a risk of long-term damage to brand loyalty.
Regulatory and Compliance Complexities
The CFPB issued a BNPL interpretive rule in 2024 addressing certain lenders as card issuers under Regulation Z. It withdrew that interpretive rule on May 12, 2025. Withdrawal does not erase separate statutory, regulatory or contractual duties.
Businesses may face additional legal or operational burdens as regulations evolve, including data-sharing agreements and Compliance Monitoring.
Operational Challenges
Higher return rates and increased volume from BNPL sales can strain Merchant operations. Businesses need robust systems to manage returns efficiently and ensure disputes are resolved quickly. Failure to do so can lead to operational bottlenecks and customer dissatisfaction.
BNPL’s hidden costs can quietly erode the profitability it promises, leaving merchants with lower-than-expected returns.
Should You Integrate BNPL into Your Business?
Integrating BNPL into your business includes higher sales and also understanding the trade-offs that exist beneath the surface. The decision-making process revolves around one critical question: Does BNPL drive enough incremental value to justify its costs?
To answer this, you must assess incremental profitability, not just incremental revenue. Increased sales volumes mean little if they fail to translate into sustained, long-term growth. This evaluation requires a granular approach:
Incremental Sales vs. Fee Absorption
Start by calculating how much additional revenue you need to generate for BNPL fees to pay off.
For example, assume a 20% contribution margin before payment fees, a 5% BNPL fee on all post-adoption sales, no baseline payment fee and no additional return or operating costs. Break-even sales growth is 5% ÷ (20% − 5%) = 33.33%, not 25%. If only incremental sales use BNPL or it replaces an existing payment fee, the threshold changes. Define which sales bear each fee before using a break-even percentage.
Customer Retention as a Measure of BNPL Success
An important, yet often overlooked metric is whether BNPL contributes to repeat business. While it may attract new customers or close an immediate Sale, its role in fostering customer loyalty is less certain. To truly gauge BNPL’s value, monitor whether:
- First-time BNPL users return to purchase without BNPL.
- The average lifetime value (LTV) of BNPL customers aligns with or surpasses traditional payment users.
If BNPL primarily drives one-time purchases rather than cultivating long-term relationships, its financial benefit diminishes over time.
Return Mitigation Strategies
The historical CFPB dollar-share statistic is not proof that your BNPL purchases will have higher return rates. Measure returns and disputes separately for your own customers. The strategic question isn’t whether returns will occur because they will, but whether your infrastructure can absorb and reduce their impact. Implement these tactics to limit financial and operational strain:
- Enhanced product descriptions: Reduce mismatched expectations.
- Clear return policies: Explain eligibility and timing before purchase. Coordinate refund processing with the lender and do not make statutory or contractual refund rights contingent on installment completion.
- Return-specific logistics channels: Optimize reverse logistics to reduce processing costs and speed up resale readiness.
These strategies directly impact BNPL’s cost-benefit equation by addressing its most significant downside: revenue erosion through returns.
Competitive Positioning with BNPL
Adopting BNPL also involves staying relevant in your market. If competitors offer BNPL, not having it may place your business at a disadvantage. However, differentiation lies in execution, not mere availability:
- Are your competitors leveraging BNPL to push premium products or upsell effectively?
- Can you combine BNPL with loyalty incentives to amplify its value proposition, such as offering discounts for BNPL customers who transition to traditional payment methods on repeat purchases?
Competing on BNPL isn’t about copying. You need to improve its strategic role within your broader payment ecosystem
Cash Flow Considerations
One of BNPL’s selling points is immediate payouts to merchants. However, merchants often fail to account for hidden cash flow risks, such as:
- Chargebacks on disputed returns: Even when the BNPL provider handles collections, unresolved disputes can lead to clawbacks.
- Fee stacking: Certain providers charge not just transaction fees but also additional processing or Settlement fees for specific cases, especially on international sales.
Assessing these risks requires combing through provider contracts carefully to ensure your understanding of payout timelines and associated costs.
Future-Proofing Your Payment Strategy
The payments landscape is evolving, and BNPL is only one facet of a larger shift toward greater flexibility at Checkout. Whether BNPL remains a competitive edge in five years depends on:
- Regulatory changes: Ongoing scrutiny by bodies like the CFPB could affect BNPL’s cost structure, Compliance burden, or customer appeal.
- Technological integrations: Emerging models such as embedded financing may supplant standalone BNPL platforms, offering similar benefits with fewer downsides.
Investing in BNPL today should align with your long-term strategy for customer experience, Compliance, and scalability, not just short-term sales bumps.
Beyond the financial math, BNPL affects how customers perceive your brand. Balancing accessibility with sustainable profitability is critical:
- Are the benefits of higher sales and wider reach sustainable after accounting for costs and return risks?
- Does your BNPL partnership enhance customer satisfaction, or does it introduce frustrations (e.g., Dispute resolution delays)?
- Can you differentiate your BNPL offering to align with your unique value proposition while minimizing risk?
With increased sales and wider market appeal on one side and higher fees and return risks on the other, your decision should be based on Clear, actionable insights.
But you don’t have to navigate this alone. At VeriFee, we specialize in payment systems and can provide the clarity you need to make informed decisions.
Here’s how we can help you master the BNPL decision:
- Transparent Cost Analysis: We’ll reveal the true costs of BNPL integration, including transaction fees, hidden charges, and their operational impact on your margins.
- Fee Negotiation: Leveraging our expertise, we can review negotiable terms and assess whether alternatives could reduce cost. Provider approval and savings are not guaranteed.
- Customer Insights: By analyzing your Transaction Data, we’ll identify whether BNPL aligns with your audience’s purchasing behaviors and business goals.
With VeriFee’s guidance, you’ll have the tools to assess BNPL’s potential while safeguarding profitability.
How to Calculate the True Cost vs. Value of BNPL for Your Business
Deciding whether BNPL is right for your business means moving beyond assumptions and using data to measure its true impact.
While BNPL offers a potential sales boost, it comes with costs that could erode profitability.
To assess whether BNPL will deliver value, you need a Clear, structured approach to calculating its financial impact. Here’s how to break it down:
Step 1: Define Key Variables
Gather baseline retained revenue, contribution margin before payment fees, current payment costs, the share of post-adoption sales using BNPL, BNPL percentage and fixed fees, incremental retained sales, refund-fee treatment and additional operating costs. Track returned dollar value separately from transaction counts and avoid charging the same lost revenue twice.
Step 2: The Equation
Incremental contribution = additional retained sales × contribution margin − change in payment costs − additional return-handling costs − other incremental operating costs.
Baseline and post-adoption periods must use the same accounting basis. Compare contribution after adoption with contribution before adoption, not with zero. A result is not guaranteed net income, EBITDA or cash flow.
Step 3: Plug in the Numbers
Use a simplified scenario with $100,000 baseline retained sales, 27% more retained sales, a 20% contribution margin before payment fees and a 5% BNPL fee on all $127,000 of post-adoption sales. Assume baseline payment fees, extra return costs and other incremental operating costs are zero solely to isolate the calculation.
Baseline contribution: $100,000 × 20% = $20,000.
Post-adoption sales: $100,000 × 1.27 = $127,000.
Post-adoption contribution before BNPL fees: $127,000 × 20% = $25,400.
BNPL fees: $127,000 × 5% = $6,350.
Post-adoption contribution after BNPL fees: $25,400 − $6,350 = $19,050.
Change from baseline: $19,050 − $20,000 = −$950.
This scenario produces more sales but $950 less contribution. Real baseline processing costs, BNPL adoption share, refunds and fixed fees can change the outcome materially.
Step 4: Interpret the Results
The original graphic model used the same $127,000 of sales and subtracted $13,208 of assumed return impact ($127,000 × 13% × 80%), leaving $5,842. That arithmetic is internally consistent, but $5,842 is not an incremental gain over the $20,000 baseline. Under those assumptions it is $14,158 below baseline. The 80% loss assumption also needs justification for recoverable merchandise and margin accounting and the historical CFPB statistic is not a forecast for all sales.
Use your own retained-sales and return-cost data instead. Distinguish payment fees retained on refunds, recoverable inventory, lost contribution and extra shipping or labor so no expense is counted twice.
Step 5: Test and Adjust
Every business is unique, so it’s critical to test these calculations with your actual numbers and specific circumstances:
Low margins? Small profit margins make absorbing BNPL fees more challenging.
High return rates? Adjust your estimates if your industry experiences higher return rates.
High ticket items? BNPL works well for expensive products where splitting payments makes purchases more accessible to customers.
Conclusion
Adding BNPL to your payment options can potentially drive higher sales and attract new customers. However, the increased fees and return risks mean that success isn’t guaranteed.
To ensure BNPL is the right fit, take the time to crunch the numbers, analyze your customer base, and evaluate its long-term impact on your bottom line.
If the math doesn’t add up, let VeriFee help you take control. With our expertise in payment systems, we help you uncover the true costs, negotiate better terms, and make data-driven decisions. Whether it’s optimizing BNPL or exploring alternative strategies, we’re here to empower your business. Contact us today.